ACA OPEN ENROLLMENT BEGAN YESTERDAY: WHAT FLORIDIANS NEED TO KNOW | | |
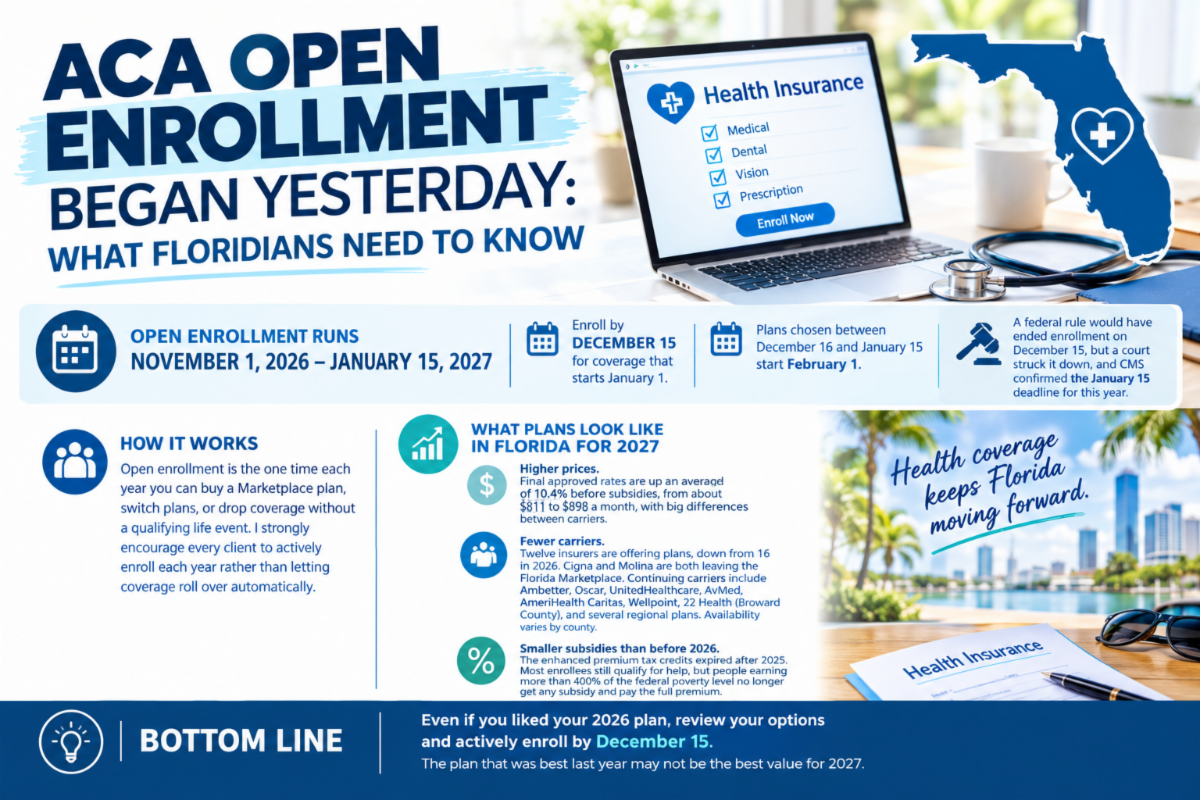
Open enrollment for 2027 Marketplace health insurance opened yesterday. It runs November 1, 2026 through January 15, 2027. Enroll by December 15 for coverage that starts January 1. Plans chosen between December 16 and January 15 start February 1. A federal rule would have ended enrollment on December 15, but a court struck it down, and CMS confirmed the January 15 deadline for this year.
How it works: Open enrollment is the one time each year you can buy a Marketplace plan, switch plans, or drop coverage without a qualifying life event. I strongly encourage every client to actively enroll rather than letting coverage roll over automatically. Premiums, networks, drug lists, and your subsidy all change every year, and your premium tax credit is based on your estimated 2027 household income, so an accurate, updated income projection matters.
What plans look like in Florida for 2027:
-
Higher prices. Final approved rates are up an average of 10.4% before subsidies, from about $811 to $898 a month, with big differences between carriers. This follows a much larger increase for 2026.
-
Fewer carriers. Twelve insurers are offering plans, down from 16 in 2026. Cigna is not offering any plans in Florida and Molina will not be offering any plans through healthcare.gov. If you have one of these Cigna or Molina plans your coverage ends December 31, and you'll need to choose a new plan for 2027. Continuing carriers include Ambetter, Oscar, UnitedHealthcare, AvMed, AmeriHealth Caritas, Wellpoint, 22 Health (Broward County), and several regional plans. Availability varies by county.
-
Smaller subsidies than before 2026. The enhanced premium tax credits expired after 2025. Most enrollees still qualify for help, but people earning more than 400% of the federal poverty level no longer get any subsidy and pay the full premium.
Bottom line: Even if you liked your 2026 plan, review your options and actively enroll by December 15. The plan that was best last year may not be the best value for 2027.
| | NEW THIS YEAR: YOUR AUTHORIZATION IS REQUIRED BEFORE I CAN HELP | | |
For 2027, CMS requires your electronic authorization before any agent can look at, renew or change your Marketplace application. This applies to every client, every year, including people who have worked with me for years. Below, I explain what these new requirements are and what you can do so your enrollment goes smoothly and quickly.
Why the changes? Over the past few years, some dishonest agents enrolled people or switched their plans without permission to collect commissions. CMS recently canceled more than 760,000 enrollments it found to be unauthorized and paused registration of new agents until February 2027. The new rules are meant to make sure you, and only you, decide who works on your coverage.
What's changing:
-
Electronic authorization. Before I can access or update your application, you'll receive a text or email asking you to approve me as your agent. Nothing moves forward until you click to approve.
-
Consent. Separately, I must have your documented consent on file before I review your information or submit an application. Consent can remain in effect indefinitely, so if you've already given me consent and it hasn't expired, you won't need to give it again. If your consent has expired or was never obtained, I'll ask for it before we begin.
-
Review and attestation. We complete your application together on Health Sherpa while you're on the phone with me. You'll verify your answers as we go, including your household, income and contact details, and you must submit your verification and authorization before I can submit the application.
-
Identity verification. CMS treats certain applications as “high risk” and requires the client to verify their identity, usually through Experian or ID.me, before authorizing an agent. An application is high risk if it is a new Marketplace application, including for someone who has moved to Florida from another state; if the client has an active enrollment with a net premium of $30 a month or less after subsidy; or if the client is working with a new or different agent. Clients who don’t fall into any of these groups won’t need to verify their identity.
-
Social Security or immigration numbers. Every applicant except newborns must have a verifiable Social Security number or immigration document number on the application.
-
Subsidy eligibility for non-citizens. Starting in 2027, the only non-citizens eligible for premium tax credits are green card holders (lawful permanent residents), certain Cuban and Haitian entrants, and COFA migrants from the Freely Associated States. Other non-citizens with an eligible immigration status on the approved list at HealthCare.gov can still enroll in Marketplace plans, but without subsidies.
How you can help: Plan to be available by phone for your enrollment, have your phone or email handy so you can approve authorization requests while we're on the line, and respond right away, since your enrollment can't proceed until you do. Have Social Security numbers or immigration documents ready for everyone on your application.
Other changes you should know about:
-
No more cap on subsidy repayment. Your subsidy is paid in advance based on the income you project. If your actual income turns out higher, you must now repay every dollar of excess subsidy when you file your taxes. Before 2026, repayment was capped for most people. If you receive a subsidy and it turns out you didn't qualify for one at all, for example because your income ended up above 400% of the federal poverty level, you'll have to pay back the entire subsidy you received. That could be thousands of dollars.
-
Estimate income carefully and report changes. Base your 2027 income projection on realistic numbers and let me know right away if your income or household changes during the year so we can adjust your subsidy.
-
You must file taxes and reconcile. Anyone who receives a subsidy must file a federal tax return with Form 8962. Starting in 2028, people who didn't file and reconcile for 2026 will lose subsidy eligibility.
-
Automatic re-enrollment with a subsidy ends after this year. Starting with 2028 coverage, federal law requires everyone who gets a subsidy to verify their income, household and eligibility before the subsidy can be applied. Anyone who doesn't will be renewed at full price, with no subsidy. Verification for 2028 is expected to open in August 2027, and I'll reach out when it's time. This is one more reason I encourage every client to actively enroll.
-
Catastrophic plans are harder to get for 2027. For 2026, people of any age who didn't qualify for a subsidy because their income was too high or too low could buy a catastrophic plan. A federal court has blocked that rule for 2027, so catastrophic plans are again limited to people under 30 and those who obtain a hardship or affordability exemption. If you're 30 or older and have a catastrophic plan this year, you'll need an exemption to keep one for 2027 or will need to choose a different plan. A new rule also allows catastrophic plans that last up to 10 years, but it's not yet clear whether any insurers will offer them.
-
Bronze and catastrophic plans are HSA-eligible. All bronze and catastrophic Marketplace plans continue to qualify for health savings accounts in 2027, so you can set aside pre-tax money for medical costs.
Please complete your Retire Flo survey. On Thursday, October 29, I sent each client a short Retire Flo survey where you can enter your doctors, medications and projected 2027 income. Retire Flo automatically populates Health Sherpa, the enrollment platform I use, with your providers, medications, and income. That gives us a much faster way to find the plans that best fit your doctors, prescriptions, and budget. If you haven't completed your survey yet, please do so as soon as possible.
When I'll start enrolling. I've traditionally begun working on client enrollments after the first week of open enrollment. In the first days, the systems often don't work properly, and errors need to be corrected before applications go through smoothly. Waiting a few days helps avoid problems with your application, and there's still plenty of time to enroll by December 15 for January 1 coverage.
| | PAYING FULL PRICE FOR ACA COVERAGE? A PRIVATE PLAN MAY COST MUCH LESS | | |
With the enhanced subsidies gone and Florida premiums rising again, many people earning too much for a subsidy are paying the full ACA price. For healthy individuals and families, private plans can be a lower-cost alternative. Other options include short-term medical, limited benefit plans, and medical cost sharing.
What are private plans? Private plans are health plans sold outside the ACA Marketplace. Unlike ACA plans, most are medically underwritten: you answer health questions, and you are either approved or not approved. The private plans I offer don't exclude or limit coverage for pre-existing conditions once you're approved, but if you don't pass underwriting, you won't be eligible for the plan. In exchange, premiums are often significantly lower than for unsubsidized ACA plans. Many of the plans I write are PPOs that use Cigna's largest PPO network, while others use the PHCS Extended PPO or First Health networks, and many can be purchased any time of year rather than only during open enrollment.
Other private options include:
-
Short-term medical plans. Temporary coverage that can bridge a gap, such as between jobs or until other coverage starts. These plans require health questions and don't cover pre-existing conditions.
-
Limited benefit plans. These pay set dollar amounts for things like doctor visits; hospital stays; or surgery. They can lower costs but are not a full replacement for major medical coverage.
-
Medical cost sharing. Members share each other's medical bills through a membership organization. These programs are not insurance, so payment of bills is not guaranteed, but monthly costs are often low.
Who they're best for:
- People who earn too much to qualify for a premium tax credit, or whose subsidy is small.
- Healthy individuals and families who can answer health questions.
- Self-employed people and small business owners. About 70% to 80% of the people who buy private plans have a business EIN, and I can offer EIN holders, even a business of one, plans that cost significantly less than other private plans.
Who should stick with the ACA: If you receive a sizable subsidy, have significant health conditions, or are pregnant or planning to be, an ACA plan is usually the better choice. ACA plans can't turn you down because of your health, and subsidies are only available on Marketplace plans.
Timing matters. Private plans require approval. If you're considering one, apply well before the January 15 open enrollment deadline. That way, if you aren't approved, you can still enroll in an ACA plan for 2027. Call me to compare a private plan side by side with your ACA options.
| | |
About Paul Cholak
Paul has over forty years of benefits experience and has been Director of Employee Benefits for large companies, as well as a benefits consultant with major consulting firms. He understands the health and life insurance needs of individuals and families of all ages. He also has considerable experience in selling health and life insurance to employer groups.
He guides you through the steps of getting health and/or life insurance and is available to help you both BEFORE and AFTER you've made your purchase decision.
| |
Contact Us
Local: 561-734-3884
Toll-free: 877-734-3884
| | | |



 HEALTH
 DENTAL
 MEDICARE
 DISABILITY
 LIFE